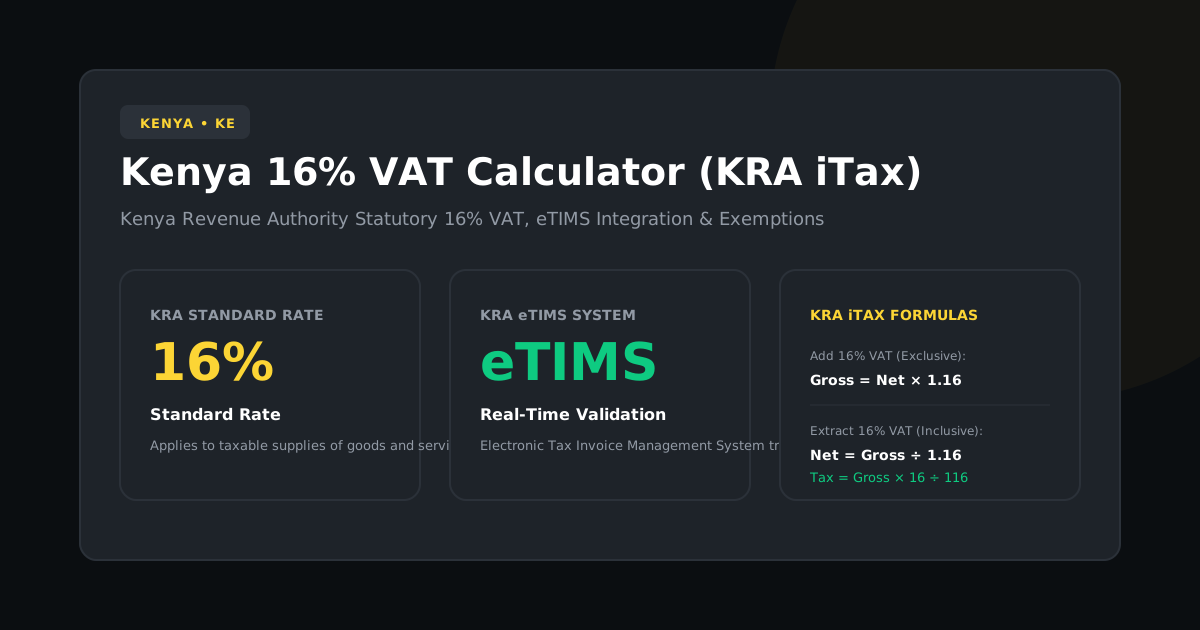
The Kenya Revenue Authority (KRA) levies Value Added Tax on taxable supplies of goods and services made in Kenya and on the importation of taxable goods. The statutory standard rate is 16%.
Following recent Finance Acts and the integration of electronic Tax Invoice Management System (eTIMS), computing 16% VAT correctly on business quotations and expense claims is essential. Our live VAT calculator delivers rapid calculations in Kenyan Shillings (KES).
KRA VAT Classification
| Classification | Rate | Eligible Transactions |
|---|---|---|
| Standard Rate | 16.0% | Commercial sales, petroleum products (fuel), electronics, professional services, hospitality, telecommunications. |
| Zero Rate (0%) | 0.0% | Exported goods and taxable services, supply of tea/coffee for export, agricultural pest control, international transport. |
| Exempt Supplies | Exempt | Unprocessed agricultural produce, financial services, medical supplies and pharmaceuticals, education services. |
How to Calculate 16% Kenya VAT
1. Adding 16% VAT (Exclusive to Inclusive)
To invoice a customer in Kenya starting from a net pre-tax amount:
• 16% VAT: KES 100,000.00 × 0.16 = KES 16,000.00
• Total Invoice: KES 100,000.00 + KES 16,000.00 = KES 116,000.00
2. Removing 16% VAT (Inclusive to Exclusive / Reverse VAT)
When auditing consumer fuel receipts or hardware purchases where only the gross total is printed:
• Net Value: KES 29,000.00 ÷ 1.16 = KES 25,000.00
• Extracted KRA VAT: KES 29,000.00 - KES 25,000.00 = KES 4,000.00
eTIMS Compliance & KRA iTax Filing
VAT-registered taxpayers in Kenya must file monthly VAT returns via KRA's iTax portal on or before the 20th day of the month following the period of tax.
Under Section 23A of the Tax Procedures Act, business expenses can only be claimed for income tax deduction if supported by an electronic tax invoice generated through an eTIMS-compliant system.