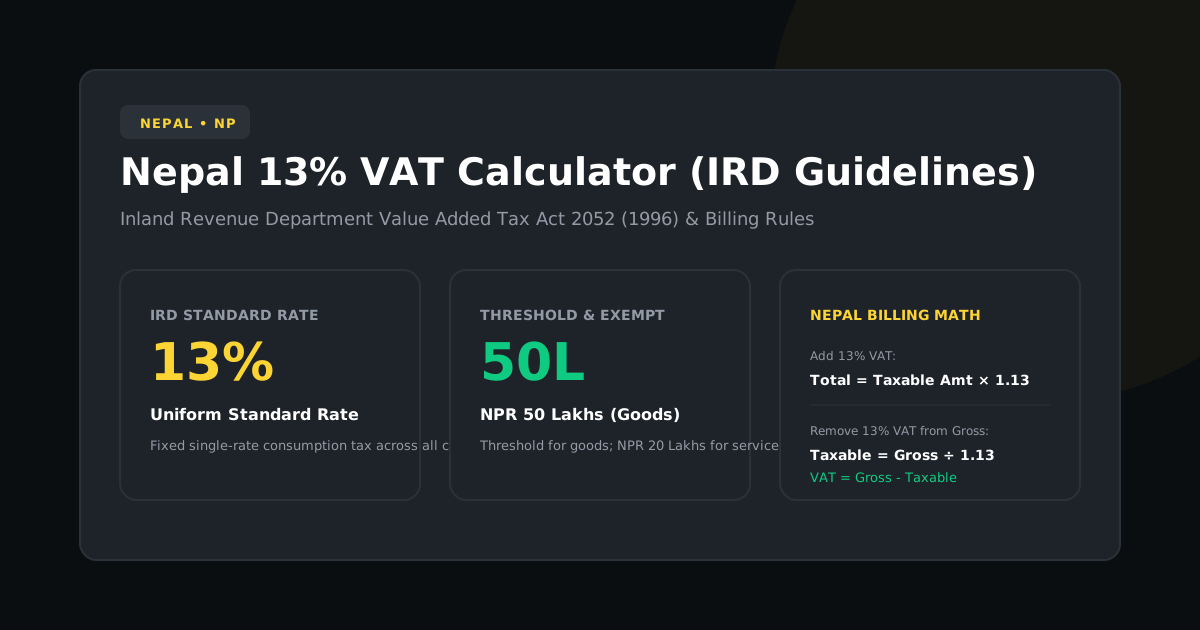
In Nepal, Value Added Tax is governed by the Value Added Tax Act, 2052 (1996) and administered across the country by the Inland Revenue Department (IRD). Nepal operates a simple single-rate statutory system of 13%.
Whether creating IRD-compliant tax bills in Nepalese Rupees (NPR) or auditing commercial expenses, our online VAT calculator provides zero-latency accuracy.
Nepal Tax Classification
| Classification | Rate | Eligible Goods & Services |
|---|---|---|
| Standard Rate | 13.0% | Commercial sales, electronics, motor vehicles, restaurant services, consulting, imported goods, construction. |
| Zero Rate (0%) | 0.0% | Direct export of goods and services, supplies to diplomatic missions and privileged international agencies. |
| Exempt Supplies | Exempt | Basic agricultural items (rice, unhusked paddy, vegetables), educational services, postal stamps, life insurance, medical health services. |
How to Calculate 13% Nepal VAT
1. Adding 13% VAT (Taxable Value to Total Bill)
To invoice a customer on a taxable item:
• 13% VAT: NPR 50,000.00 × 0.13 = NPR 6,500.00
• Total Bill Payable: NPR 50,000.00 + NPR 6,500.00 = NPR 56,500.00
2. Removing 13% VAT (Gross Bill to Net Taxable Base)
To compute the net taxable amount from an inclusive consumer bill:
• Net Taxable Base: NPR 11,300.00 ÷ 1.13 = NPR 10,000.00
• Extracted VAT (13%): NPR 11,300.00 - NPR 10,000.00 = NPR 1,300.00
PAN & VAT Invoicing Rules in Nepal
Entities operating businesses in Nepal obtain a 9-digit Permanent Account Number (PAN). When annual sales surpass the statutory thresholds (NPR 5 million for goods, NPR 2 million for services), businesses must obtain a VAT Certificate from the IRD.
Under IRD billing directives, registered businesses must issue sequential tax bills bearing the business PAN, tax breakdown, and date of transaction. VAT returns must be submitted by the 25th day of each Nepali calendar month (Baisakh to Chaitra).