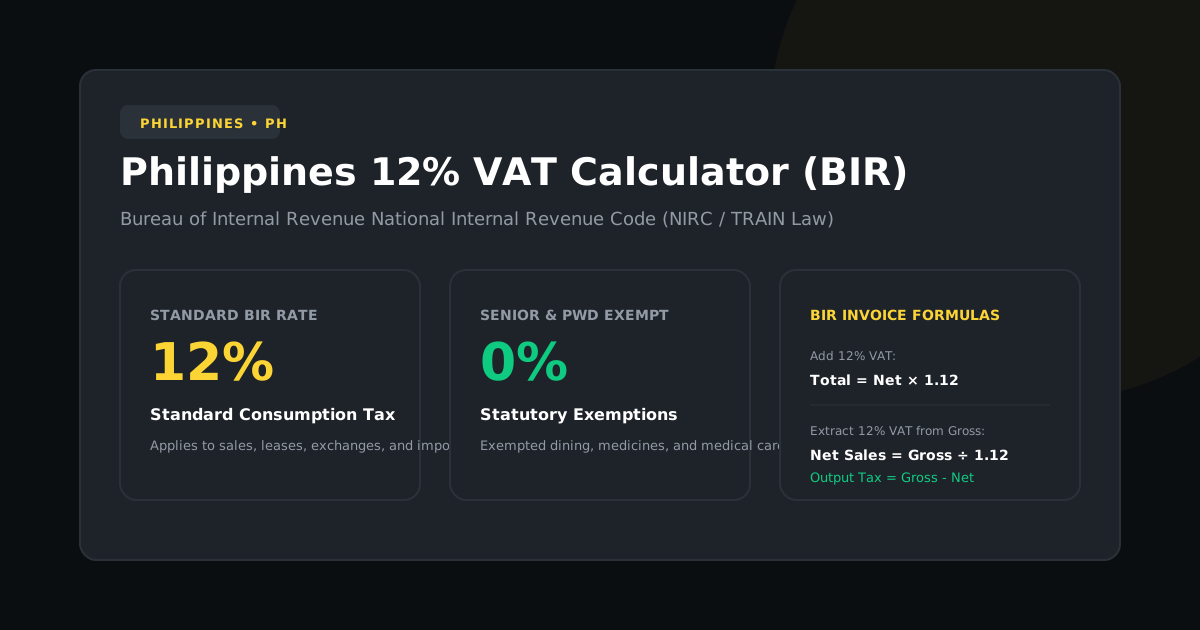
In the Republic of the Philippines, Value-Added Tax is imposed on any person or entity who, in the course of trade or business, sells, exchanges, barters, or leases goods, properties, or services. The uniform statutory standard rate is 12%, administered by the Bureau of Internal Revenue (BIR).
Whether reconciling official BIR receipts, filing quarterly returns, or issuing quotations, our real-time VAT calculator ensures 100% mathematical precision with zero delay.
Philippine VAT Rate Breakdown
| Classification | Rate | Eligible Transactions |
|---|---|---|
| Standard Rate | 12.0% | Domestic sales of goods, commercial leases, consultancy, legal services, hospitality, consumer electronics. |
| Zero-Rated (0%) | 0.0% | Direct export sales, services rendered to persons engaged in international shipping, sales to PEZA economic zones. |
| VAT-Exempt | Exempt | Agricultural food products in original state, medical and hospital services, educational institutions, sales below ₱3M threshold. |
How to Calculate 12% VAT in the Philippines
1. Adding 12% VAT (Vatable Sale to Gross Total)
To invoice a customer starting from a net vatable sales amount (excluding tax):
• 12% VAT: ₱25,000.00 × 0.12 = ₱3,000.00
• Total Invoice: ₱25,000.00 + ₱3,000.00 = ₱28,000.00
2. Extracting 12% VAT (Gross Receipt to Net Vatable Sales)
Official receipts from restaurants, retail, and commercial stores in the Philippines display the total gross amount collected:
• Net Vatable Sales: ₱1,680.00 ÷ 1.12 = ₱1,500.00
• 12% VAT: ₱1,680.00 - ₱1,500.00 = ₱180.00
TRAIN Law Thresholds & Percentage Tax
Republic Act No. 10963 (TRAIN Law) permanently set the mandatory VAT registration threshold at ₱3,000,000 in gross annual sales.
Small businesses earning ₱3,000,000 or less per year are classified as non-VAT taxpayers. Instead of charging 12% VAT, non-VAT businesses pay a 3% Percentage Tax under Section 116 of the Tax Code, filing BIR Form 2551Q quarterly.