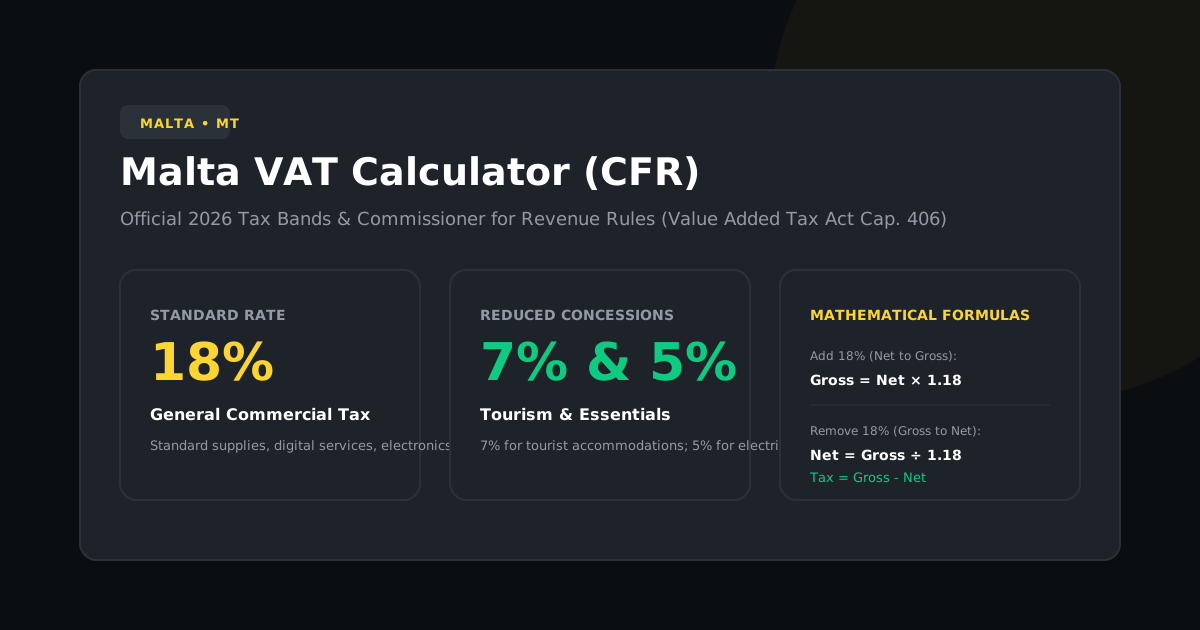
As a prominent European commercial hub and maritime center, Malta levies Value Added Tax under the supervision of the Commissioner for Revenue (CFR). The standard statutory rate is 18%, complemented by 7% and 5% reduced rate tiers.
Whether invoicing iGaming vendors, hospitality guests, or corporate service recipients in Euros (€), our free online VAT calculator computes accurate additions and subtractions without server requests.
Malta Statutory VAT Schedule
| Tier | Rate | Covered Goods & Services |
|---|---|---|
| Standard Rate | 18.0% | General commercial goods, automotive sales, digital services, electronics, consulting, legal and auditing services. |
| Reduced Rate (Tourism) | 7.0% | Hotel accommodations, holiday rental premises, licensed guest houses, tourist camp sites. |
| Reduced Rate (Essentials) | 5.0% | Electricity supply, medical items, confectionery, printed & digital books, periodicals, care for disabled persons. |
| Zero Rate (0%) | 0.0% | Exports outside the EU, intra-community EU supplies, international transport, pharmaceuticals, basic human food. |
How to Calculate 18% Malta VAT
1. Adding 18% VAT (Net to Gross)
To invoice commercial clients in Malta:
Add 18% Formula
Gross = Net × 1.18 | 18% VAT = Net × 0.18
Example: A professional consulting fee of €3,000.00 Net:
• 18% VAT: €3,000.00 × 0.18 = €540.00
• Gross Total Due: €3,000.00 + €540.00 = €3,540.00
• 18% VAT: €3,000.00 × 0.18 = €540.00
• Gross Total Due: €3,000.00 + €540.00 = €3,540.00
2. Removing 18% VAT (Gross to Net)
To extract 18% VAT from a gross receipt:
Remove 18% Formula
Net = Gross ÷ 1.18 | 18% VAT = Gross - Net
Example: A purchase receipt totaling €708.00 Gross:
• Net Subtotal: €708.00 ÷ 1.18 = €600.00
• Deductible VAT: €708.00 - €600.00 = €108.00
• Net Subtotal: €708.00 ÷ 1.18 = €600.00
• Deductible VAT: €708.00 - €600.00 = €108.00
Article 10 vs Article 11 Registration in Malta
Businesses established in Malta register for VAT under either:
- Article 10: Standard VAT registration with full right to deduct input tax. Mandatory when turnover exceeds statutory thresholds (€35,000 for goods, €30,000 for economic services).
- Article 11 (Exempt Persons): Small businesses operating below the threshold who do not charge VAT on sales and cannot claim input tax deduction.
Frequently Asked Questions About Malta VAT
When must Malta VAT returns be submitted?
Taxable persons registered under Article 10 file quarterly VAT returns through the CFR electronic portal within six weeks following the close of each tax quarter.
Does Malta apply reverse charge to cross-border EU supplies?
Yes. Under the EU VAT Directive, B2B services received by Maltese businesses from foreign EU suppliers are subject to reverse charge accounting.